
Rent A Center
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
Rent A Center - Screenshots
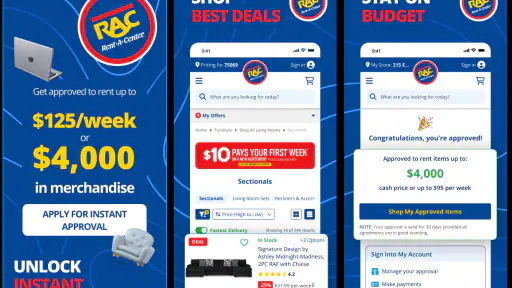
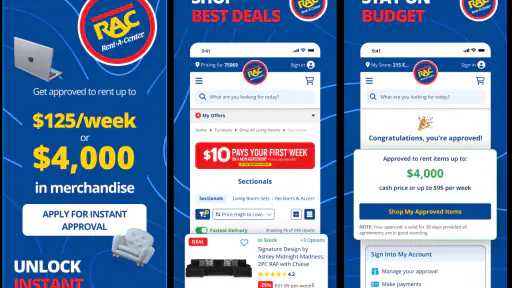
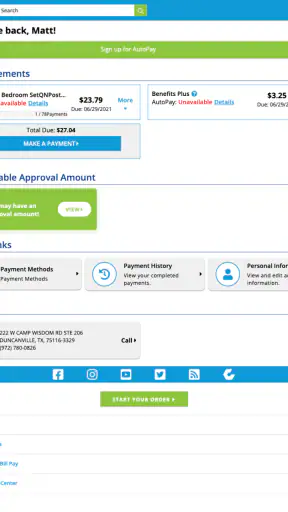
Pros
- Flexible payment options can make expensive items more accessible.
- Wide selection of furniture
- electronics
- appliances
- and computers.
- Home delivery and setup are available for many purchases.
- No traditional credit check may help some shoppers qualify.
- Online account tools make payments and order management convenient.
Cons
- Total rent-to-own costs can greatly exceed the item's cash price.
- Missed payments may lead to late fees or loss of the rented item.
- Contract terms and ownership conditions require careful review.
- Availability
- pricing
- and services can vary between store locations.
- Returning an item early may not eliminate all remaining financial obligations.
Rent A Center - Description
- App Name
- Rent A Center
- Package Name
- com.rac.racmobile
- Developer
- Rent-A-Center
- Category
- Shopping
- Last Updated
- Jan 2, 2018
- Version
- 1.5.21
When I first opened Rent A Center, I understood the appeal quickly: it is a shopping app built around getting well-known household products through smaller payments rather than paying the full cost at once. That makes it different from a standard retail app, where the main question is usually whether an item is in stock and affordable today. Here, the more important question is whether the payment arrangement fits my budget over time.
Rent A Center is a free shopping app from Rent-A-Center, and I found it most useful as a way to browse products, think through a purchase, and decide whether this kind of financing suits a particular need. It is available for Everyone, runs on Android devices using version 6.0 or later, and has reached more than a million installs. Its average rating sits at 4.6 from roughly sixteen thousand ratings, which suggests that plenty of shoppers find the experience worthwhile, although a strong rating alone does not remove the need to read the agreement carefully.
How Rent A Center Holds Up Beyond the First Week
The first-week appeal is convenience with a different budget mindset
During the first few sessions, the biggest attraction is not a clever interface trick. It is the change in how I look at a purchase. Instead of waiting until I have enough money for a large upfront payment, I can explore the possibility of taking home a major item through smaller payments and without relying on traditional credit. That can be meaningful when a refrigerator, sofa, television, appliance, or other household product becomes necessary at an inconvenient time.
The app makes more sense for planned browsing than for casual window-shopping. I would open it with a specific need in mind, such as replacing a broken appliance or furnishing a room, then compare the available choices with what I can realistically manage each pay period. That approach prevents the small-payment presentation from becoming an excuse to buy something I do not actually need.
One useful habit is to separate two decisions that are easy to mix together: choosing the product and accepting the payment arrangement. I would first decide whether the item itself is suitable, then consider the total commitment and timing of payments. A lower payment can feel comfortable while the overall obligation remains expensive compared with saving and buying outright. The app is helpful for starting that conversation with myself, but it should not replace a written budget.
The first-week experience is also a good time to check whether the catalog matches the kind of shopping I do. Someone looking for a single low-cost accessory may find a regular retailer faster and simpler. Someone trying to solve a larger household problem, especially without a conventional credit card, has a clearer reason to keep using this app. That distinction matters because the service is not really competing with every shopping app; it is competing with delayed purchases, store visits, and other ways of spreading out a large expense.
What I would check before committing
I would not stop at the product image or the recurring payment shown during browsing. Before agreeing to anything, I would read the full terms, confirm the payment schedule, and calculate the total amount over the complete agreement. I would also check what happens if my circumstances change. A payment that fits today may become difficult after an unexpected bill, reduced hours, or another household commitment.
This is one of the app's less exciting but more important uses: it gives me a place to slow down before making a decision. A physical store can create pressure to decide while standing in front of a salesperson. A phone lets me pause, compare options, and discuss the purchase with someone else. I would take screenshots or keep personal notes about the item and payment details for my own records, while still treating the official agreement as the document that controls the transaction.
Another practical tip is to compare the payment plan with at least one ordinary alternative. I might check a conventional retailer, a used-item marketplace, or a savings plan. The best choice depends on urgency and total cost. If I need an essential appliance immediately and cannot use standard credit, the app may solve a real problem. If the purchase is optional and I can wait, saving first may be financially healthier.
Month-to-month value depends on real household needs
After the novelty fades, the app's value becomes less about browsing and more about whether it helps me manage an actual purchase. I would expect to return when a household item needs replacing, when I move, or when I need furniture or electronics before I have saved the full amount. In those situations, a shopping app focused on smaller payments can remain relevant because the underlying need is practical rather than entertainment-driven.
The strongest recurring use case is planning around a known gap. Imagine my washing machine stops working shortly before payday. Waiting may create extra laundry costs or disrupt work and family routines. I could use the app to look for a replacement, estimate whether the payment schedule fits, and decide whether the immediate convenience justifies the longer commitment. That is a realistic reason to keep the app installed: it can be a backup tool for expensive household surprises.
Still, I would not treat it as a daily shopping destination. Most people do not need to browse rent-to-own products every week, and repeated browsing can encourage unnecessary upgrades. The app earns a lasting place on my phone only if I use it as a focused resource when a larger purchase is genuinely needed. Otherwise, a browser bookmark or a conventional store app may be enough.
Its month-to-month usefulness also depends on how clearly I track the commitment outside the app. I would add each payment to my regular budget, set a reminder in my calendar, and keep the agreement details somewhere accessible. This is a small but important workflow improvement: the app may help me arrange the purchase, but my calendar and budget are what help me live with it responsibly.
Where it compares well with ordinary shopping apps
Compared with a typical retailer, Rent A Center is more relevant when the buyer's main obstacle is upfront cost or access to traditional credit. A normal shopping app may offer a wider range of products or a simpler one-time checkout, but it generally assumes that the customer can pay through the available methods. This app speaks to a different situation, where spreading payments is central to the decision.
Compared with a credit card, the experience may feel more approachable to someone who does not have a card or does not want to use one. However, “without credit” should not be interpreted as “without responsibility.” A payment agreement still creates an obligation, and the total cost, timing, and consequences of missed payments deserve the same attention I would give any financial commitment.
Compared with buying used, the app may offer a more straightforward path to obtaining a particular household product, but used goods can sometimes cost less overall. Compared with saving and paying cash, it provides speed but usually asks me to accept a longer commitment. There is no universal winner. The right option depends on urgency, reliability, total cost, and how stable my income is.
Maintenance is mostly financial and organizational
The app itself does not demand constant care in the way a fitness tracker or social network does. I do not need to open it every day to keep receiving value. The real maintenance burden is managing the agreement after the initial purchase. That means remembering payment dates, keeping contact details current, checking account activity, and reviewing the terms if anything about the arrangement changes.
This is where the app can quietly become less convenient than it first appears. A small recurring payment is easy to overlook, especially when several subscriptions and bills already leave my account each month. I would create a separate budget line for the item instead of mentally grouping it with general shopping. If the app or account area displays payment information, I would review it periodically rather than assuming everything is progressing correctly.
I would also keep the phone and app updated. The current version is 1.5.21, and the application has been available since January 2, 2018, so it is not a brand-new service trying to prove that it can survive beyond launch. Even so, an older supported device may provide a different experience from a newer one. Since the minimum Android requirement is 6.0, compatibility is broad, but performance and display quality can still vary between phones.
For someone who changes phones often, the important preparation is not relying on the device alone. I would keep my account access information secure and retain personal records of the agreement. That makes the arrangement easier to manage if I replace my phone, lose access temporarily, or need to review an earlier purchase. The app can be convenient, but the purchase should remain understandable without having to remember every screen I saw during checkout.
Sources of fatigue that become clearer over time
The first source of fatigue is financial repetition. The initial payment may feel manageable, but the commitment remains present long after the excitement of bringing home a new product disappears. If I use this type of arrangement for several purchases at once, the individual payments can combine into a much heavier monthly burden. I would avoid stacking agreements unless I could still cover them comfortably after rent, utilities, food, transport, and savings.
The second is decision fatigue. Shopping through smaller payments can make more items appear reachable, which increases the temptation to compare products that were not part of my original plan. I found it more sensible to write down the exact problem I am solving before opening the catalog. “I need a working refrigerator” is a useful goal; “I want to see what I can get this month” is much more likely to lead to an unnecessary commitment.
A third concern is that the app's convenience may shift attention away from ownership economics. I would ask whether I need the newest version, whether a less expensive model would do the job, and whether buying second-hand is acceptable. These questions are not criticisms of the app's basic purpose; they are safeguards against confusing access with value.
There can also be friction when I want a quick, ordinary purchase. If the item is inexpensive, waiting for delivery or arranging a payment plan may be more work than paying directly at another retailer. The app earns its place when the product is important enough, the upfront cost is a genuine barrier, and the payment structure is clear. For small impulse purchases, it is usually the wrong tool.
Who should use it, and who should choose something else
I would recommend trying Rent A Center to shoppers who need a larger household item soon, prefer smaller payments, and do not want to depend on conventional credit. It can also suit people who want to research a purchase from home before discussing it with family members. The free download removes an initial cost, and the Everyone age rating makes it broadly accessible, although the financial decision itself should be made by an adult who understands the obligation.
I would be more cautious for anyone with an unstable income, several existing payment plans, or a habit of focusing only on the amount due each period. In those situations, saving for a cash purchase, choosing a less expensive used item, or using a transparent conventional financing option may be safer. The app is not a substitute for affordability; it is a way of structuring a purchase when affordability has been considered carefully.
I would also steer frequent bargain hunters toward comparison shopping first. The convenience of one catalog is valuable, but it can hide the opportunity to find a lower total price elsewhere. My preferred workflow is to identify the required features, compare the same type of product outside the app, and then return to the payment option only if it solves a real timing or credit problem.
Does it earn lasting space after the novelty fades?
My long-term opinion is positive but selective. Rent A Center is not an app I would open for entertainment, and I would not keep it installed simply because shopping is convenient. Its lasting value comes from a specific service: helping me explore access to larger purchases through smaller payments when paying upfront or using traditional credit is not practical.
The app's strong user response and broad reach make it easier to take seriously, but popularity does not turn a payment plan into a bargain. My recommendation is to use it with a calculator, a written budget, and a comparison against cash, used, and conventional retail alternatives. Those extra steps take only a little time and can prevent a comfortable-looking payment from becoming an uncomfortable long-term commitment.
The best reason to keep this app is preparedness, not constant shopping. I would install it when I expect a major household purchase, use it to investigate realistic options, and remove it later if I have no reason to browse. For the right shopper, that focused role is enough to justify a place on the phone. For someone who can wait, save, and pay less through another route, a normal retailer or savings plan will usually be the better long-term choice.
In short, Rent A Center succeeds when it matches a genuine need with disciplined planning. I appreciate the flexibility and the ability to explore purchases without relying on traditional credit, but I would never judge an item only by its recurring payment. Read the terms, calculate the total, keep the payments visible in your budget, and compare alternatives. Used that way, this shopping app can remain useful well beyond its first week instead of becoming another source of monthly fatigue.
FAQ
What is Rent-A-Center, and what can I use the app for?
Rent-A-Center is a shopping and account-management app connected to Rent-A-Center’s rent-to-own services. After installing it, users can browse available products such as furniture, appliances, electronics, and computers, check pricing or lease information, locate nearby stores, and manage an existing agreement. The exact products, payment options, and services shown may vary depending on your location and account status.
Do I need a Rent-A-Center account to use the app?
You can generally explore products, store information, and other public sections without immediately creating an account. However, features related to managing a rental agreement, viewing payment details, making payments, checking account information, or contacting a store may require registration and verification. Before signing up, review the information requested and make sure your personal details match the information associated with your Rent-A-Center account.
Can I make payments or manage my rental agreement through Rent-A-Center?
The app is designed to provide convenient access to account-related services, which may include reviewing agreement information, checking upcoming payments, making eligible payments, and contacting Rent-A-Center. Available functions can differ by account, state, device, and app version. Users should carefully confirm payment amounts, dates, and confirmation messages, and retain receipts or screenshots until the transaction appears correctly in their account.
What products and rent-to-own options are available in the app?
Rent-A-Center commonly offers categories such as living-room furniture, bedroom furniture, appliances, televisions, computers, and other household electronics. Product availability, colors, brands, delivery options, and total costs may differ between stores and locations. Since rent-to-own agreements can cost more over time than an outright purchase, compare the total agreement cost, payment schedule, ownership terms, and renewal conditions before accepting an offer.
Is Rent-A-Center safe to download, and what should I know about privacy?
Download the app only from the official Google Play Store or Apple App Store, and verify that the developer information matches Rent-A-Center before installing it. The app may request access to personal, account, contact, device, or payment-related information to provide its services. Review the current privacy policy and permissions, use a strong password, avoid signing in on shared devices, and keep the application updated for security and compatibility.


